SEBI has made it optional for some listed issuers to appoint a merchant banker for private placements of debt securities, according to a Corplawupdates summary of a circular dated 7 October 2026. The circular replaces paragraph 1.3 of Chapter V of the master circular for non-convertible securities dated 15 October 2025 and applies with immediate effect, with no transition period. Spectate Media has not seen the circular itself.
The default rule
A merchant banker stays the default for private placements of debt securities and non-convertible redeemable preference shares. A qualifying issuer "may not appoint" one if it meets all five conditions below.
The five conditions
- The issuer is registered or regulated by SEBI, the RBI, IRDAI or PFRDA.
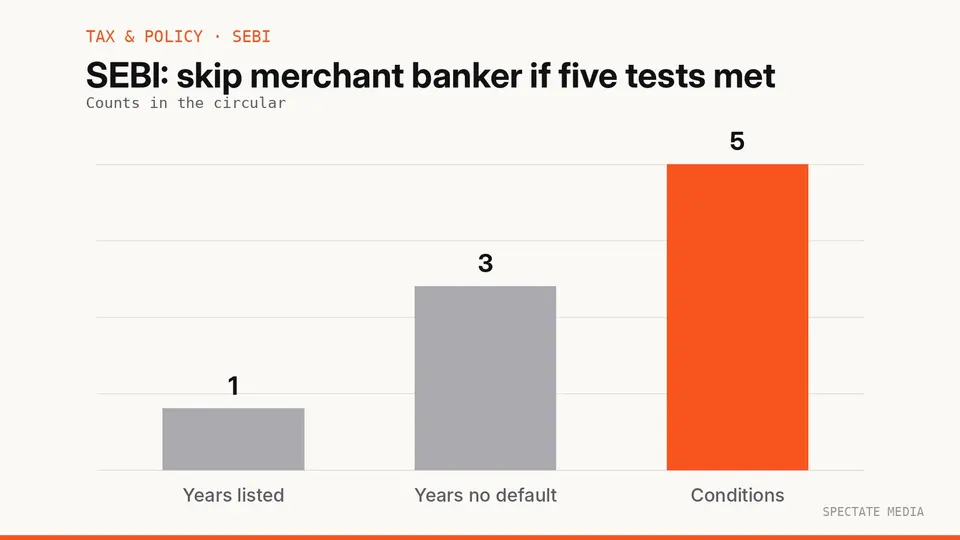
- It has been listed in a recognised exchange segment for at least one year, with no pending SEBI or exchange fines or penalties under the listing regulations.
- It has not defaulted in the last three financial years or the current one, backed by a certificate from its statutory auditor to the exchange.
- The debt is senior and secured by a first or pari passu charge on identifiable assets. Central and state public sector companies and statutory bodies may issue secured or unsecured debt.
- The debt is rated at least AA- on the placement date, and the lowest rating counts if there are several. AAA, AA+ and AA qualify, and A+ and below do not.
Who is affected
All other issuers get no relief and must still appoint a merchant banker. Stock exchanges must specify disclosure formats and confirm listing and penalty status when they give in-principle approval, and depositories are advised to amend their bye-laws and systems.
What the summary leaves open
It flags three open points: whether issuers of preference shares can use the exemption, since conditions 4 and 5 refer only to the debt security, how pending penalties under appeal are treated, and whether an earlier condition on coupon and maturity still applies.
Key numbers
- Conditions to meet: 5 (All must be met)
- Minimum rating: AA- (Lowest rating counts)
- Minimum listing period: 1 year (With no pending penalties)
- Default look-back: 3 years plus current (Auditor certificate)
What boards and CFOs should note
Three points stand out. First, high-rated, regulated and clean-record issuers can now save the cost of a merchant banker. Second, the auditor's no-default certificate has to be ready. Third, a downgrade below AA- brings the requirement back.
Source: Corplawupdates, 7 October 2026. This is a summary of a news report, published as general information. It is not legal, tax or investment advice.
This article is journalism and commentary. It is not a recommendation to buy or sell any security, and it is not professional advice. Read the full disclaimer.