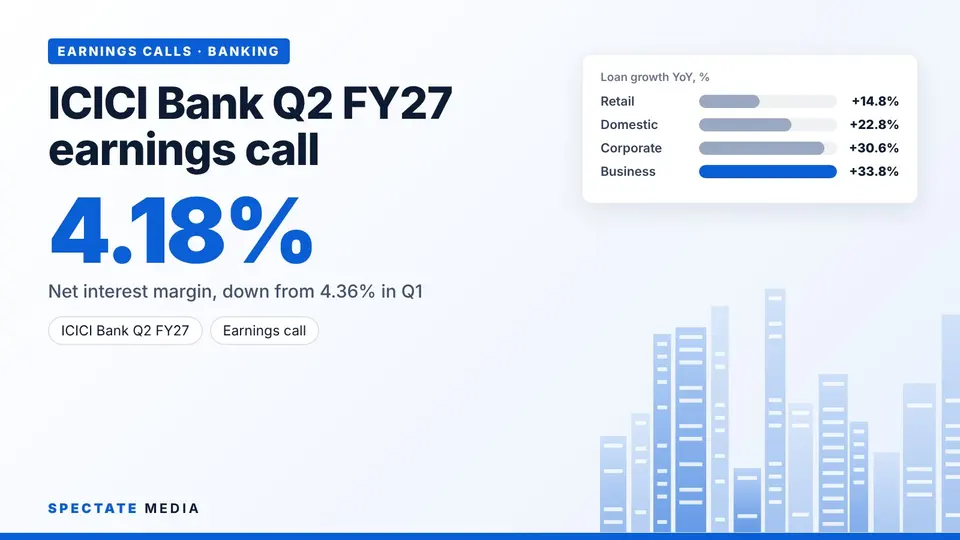
ICICI Bank reported standalone profit after tax of ₹14,843 crore for the quarter ended 30 September 2026, up 20.1% year on year, on its call of 17 October. Consolidated profit after tax was ₹16,333 crore, up 22.3%. Net interest income was ₹25,339 crore, up 17.7% year on year and 3.9% on the quarter. Net interest margin was 4.18%, against 4.36% in the first quarter and 4.30% a year earlier. Management said the domestic margin, excluding a tax-refund benefit in the first quarter, was 4.32%.
Total loans, including international branches, grew 30% year on year and 12% on the quarter. Excluding lending against FCNR(B) deposits, loans grew 24.1%. Domestic corporate loans rose 30.6% and business banking 33.8%, while retail and rural loans rose 14.8%. Total deposits rose 27.1% year on year, and about $18 billion was mobilised through FCNR(B) deposits under the RBI swap facility. The net NPA ratio was 0.30%, against 0.35% in the first quarter and 0.39% a year earlier. Provisions were ₹851 crore, and the CET1 ratio was 16.01%.
On the outlook, management said margins will moderate further in the third quarter and recover from the fourth quarter. Spectate Media has not seen ICICI Bank's own filed transcript. This summary is based on a third-party copy of the transcript, which the publisher says was produced partly with AI assistance and contains a few garbled passages. It contains no direct quotes for that reason, and the figures should be checked against the bank's filings.
Positives
- Profit growth held at about 20%. Standalone profit after tax rose 20.1% and consolidated profit 22.3% year on year.
- Asset quality improved. The net NPA ratio fell to 0.30%, and provisions were 0.2% of average advances.
- Corporate and business banking led growth. Domestic corporate loans rose 30.6% and business banking 33.8%, and management said corporate returns are not worse than retail.
- Capital stayed strong. The CET1 ratio was 16.01% and the total capital ratio 16.68%.
Watch-points
- Margins are expected to fall again in the third quarter. Management said the full-quarter effect of FCNR(B) funding and a larger overseas book will weigh, with a recovery from the fourth quarter.
- Overseas lending earns far less. Management put overseas branch margins at about 1%, against over 4% in India, and did not quantify the FCNR(B) drag on the overall margin.
- Deposit mix is shifting. The CASA ratio fell as term deposits grew, and average CASA grew 10.7% against average deposit growth of 21.2%.
- Some retail lines are weak. Credit cards fell 9.7% year on year, which management attributed to timing, and the insurance subsidiary's general insurer combined ratio was 107%.
Source: ICICI Bank Q2 FY27 earnings call transcript (Motley Fool copy).
This is a summary of a company earnings call, published as general information. It is not investment advice or a recommendation to buy or sell any security. Read the full transcript before relying on any point.
This article is journalism and commentary. It is not a recommendation to buy or sell any security, and it is not professional advice. Read the full disclaimer.